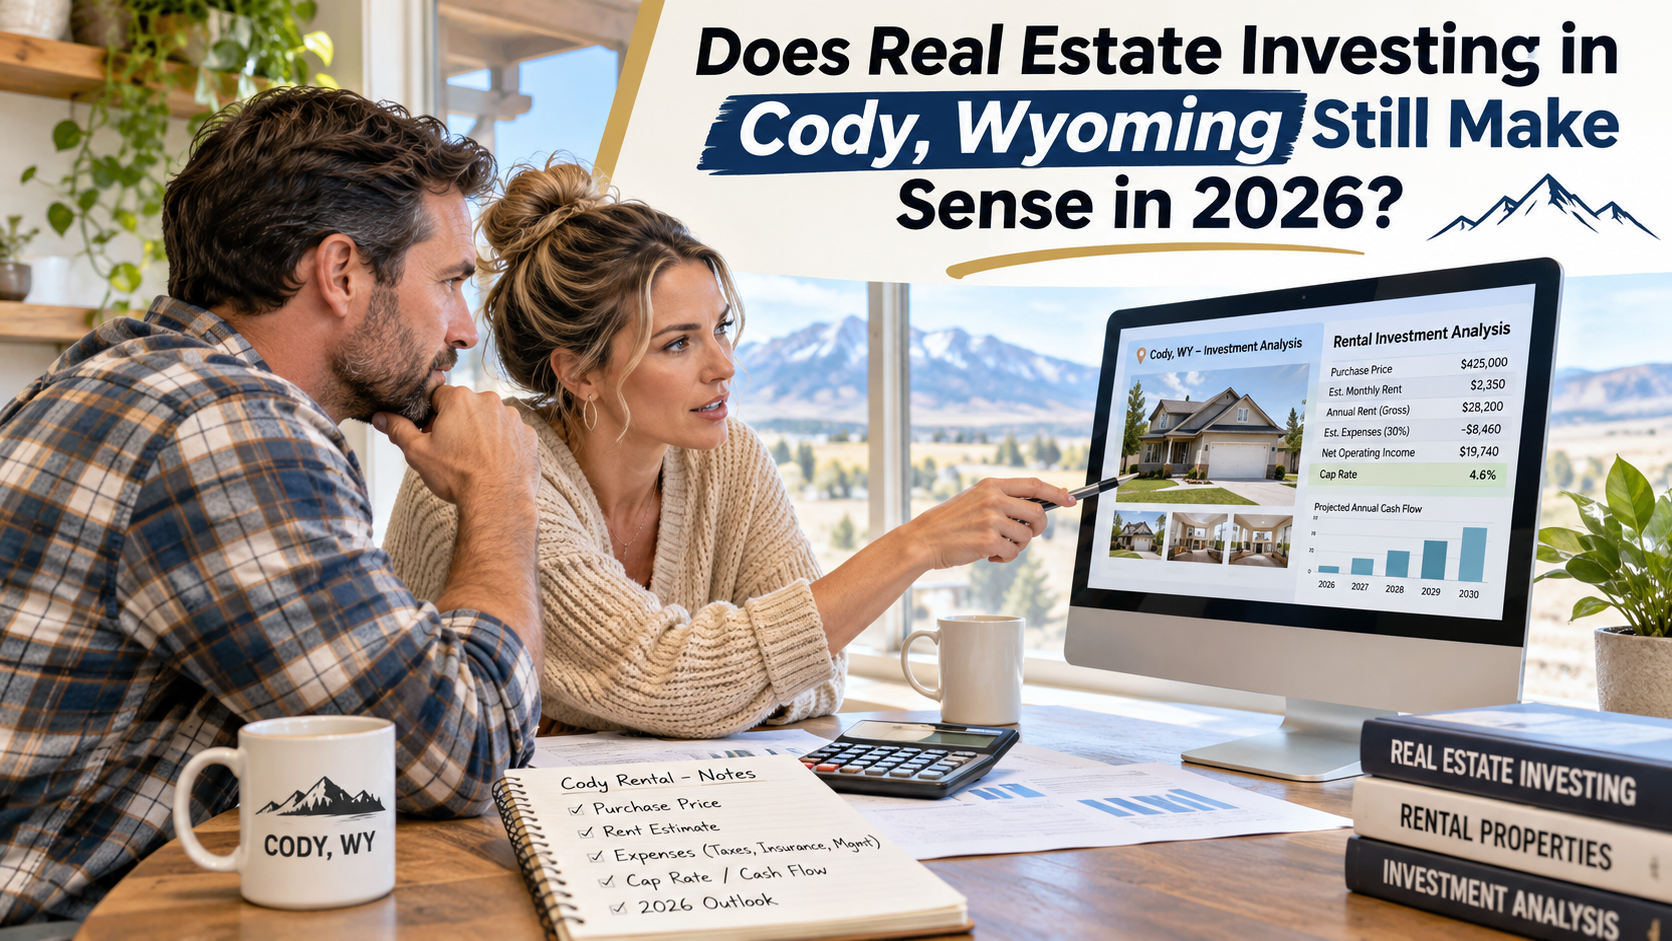
Does Real Estate Investing in Cody, Wyoming Still Make Sense in 2026?
Cody real estate is not cheap.
That does not mean Cody is a bad place to invest. It means investors have to be much more disciplined about the numbers than they were when homes could be purchased for substantially less and at lower rates.
The question is no longer, “Is Cody a desirable place to own real estate?”
It clearly is.l
The better question is:
“Does this particular property make sense as an investment in today's market?”
And that answer requires looking at more than monthly cash flow.
Rental real estate can build wealth in several ways:
Monthly cash flow
Loan principal reduction paid by the tenant
Long-term property appreciation
Potential tax deductions and depreciation
Rent growth over time
Improvements that increase value or income
Leverage—the ability to control a larger asset with a smaller amount of invested capital
A property does not necessarily have to produce large monthly cash flow to be a worthwhile investment. In fact, you can actually "lose" money every month and still build long-term wealth!
Investors need to understand where their expected return is actually coming from.
1. Do Rental-Property Numbers Still Work in Cody?
Yes—but it depends on the property and your goals.
As of fall 2026, Cody home prices remain high relative to local rents. That makes it difficult for a typical single-family rental purchased with conventional financing to generate strong monthly cash flow.
But cash flow is only one part of the equation.
An investor may accept modest cash flow—or even a small, planned negative cash flow—if the property provides strong long-term potential through principal paydown, appreciation, tax benefits, future rent increases, or improvements that create additional equity.
The key word is planned.
There is a major difference between deliberately buying a long-term investment that produces little cash today and accidentally buying a property that loses money because the investor underestimated expenses.
The best opportunities are properties with more than one advantage: below-market purchase price, multiple rental units, the potential to add value to the property, seller financing, unusually strong rent, additional income opportunities, or a lower acquisition cost.
The key is understanding how to evaluate the property's potential from every angle.
2. Current Cody Purchase Prices
Two current market sources put Cody's typical sale price in roughly the same range.
Redfin reported a $462,129 median sale price for Cody for the three-month period ending October 2026. Realtor.com reported a $471,406 median sold price for September 2026.
That is an important starting point for investors because a $450,000-plus acquisition requires substantially more rental income than a $250,000 or $300,000 property.
Financing is also working against investors. Freddie Mac's national average 30-year fixed mortgage rate was 7.11% as of November 12, 2026. Investment-property rates and terms can differ and are often less favorable than owner-occupied financing.
The combination of high prices and expensive financing is the biggest reason many Cody single-family properties do not produce immediate cash flow.
However, a higher purchase price does not eliminate the other components of investment return.
If an investor buys with financing, part of each mortgage payment reduces the loan balance. Over time, that can create meaningful equity even if the property's monthly cash flow is modest.
Historically, rent rates increase over time and even a negative cash flow can turn positive.
As the property appreciates, the investor may benefit from both debt reduction, increasing property value, and increasing cash flow at the same time.
That is one reason rental real estate should not be judged solely on whether it produces $100 per month in cash today.
3. What Are Typical Cody Rents?
American West Realty & Management's own marketed-rental data provides a larger local sample than many public rental websites.
For properties marketed from January 1 through August 8, 2026, our data showed:
Cody: 48 rentals, averaging approximately $1,389 per month, with a median of approximately $1,270.
Powell: 13 rentals, averaging approximately $1,239 per month, with a median of approximately $1,250.
Among houses in that sample, Cody two-bedroom properties averaged approximately $1,453, while three-bedroom houses averaged approximately $1,933. Powell two-bedroom houses averaged approximately $1,256, and three-bedroom houses approximately $1,703.
Those numbers should not be treated as a rent quote for a particular property. Size, age, condition, layout, garage space, yard, utilities, location, pets, amenities, and many other factors can change the market rent significantly.
More importantly, today's rent is only the starting point.
If rents increase over a long holding period while the investor's fixed-rate mortgage payment remains relatively stable, a property that produces little cash flow initially may become considerably stronger later.
That is sometimes called cash-flow growth or yield on cost improvement.
Investors should not assume aggressive rent increases, but they should recognize that a 10- or 20-year investment should not be evaluated solely on the first year's income.
4. Cody's Rent-to-Price Ratio
One quick screening tool is the monthly rent-to-purchase-price ratio.
Using Cody's approximately $462,000 median sale price and American West's approximately $1,389 average marketed rent produces a citywide ratio of only about:
0.30% per month
That is not a cap rate or a complete investment analysis. We are comparing broad market averages rather than the same properties.
But it illustrates the challenge.
A property renting for $1,900 per month would need to cost about $380,000 just to reach a 0.50% rent-to-price ratio.
At a $450,000 purchase price, that same $1,900 rent represents only about 0.42%.
The old "1% rule"—monthly rent equal to 1% of the purchase price—is largely unrealistic for conventional Cody residential properties today. However, I've been investing in Cody since 2004, and the 1% rule is a rare exception, even in the best of times, because Cody's value is more in appreciation.
The 1% rule measures gross income relative to purchase price. It does not measure principal reduction, appreciation, tax treatment, leverage, future rent increases, or value created through improvements.
That is why I consider rent-to-price ratio a useful screening tool, not a final investment decision.
An investor seeking maximum immediate cash flow may reject a property with a 0.40% ratio.
Another investor with a 15-year horizon may accept it if the property has strong appreciation potential, favorable financing, stable tenants and a reasonable total return.
The important thing is knowing which strategy you are pursuing.
5. Property Taxes Are Relatively Favorable
Wyoming's property-tax structure remains one of the more favorable parts of the investment equation.
Park County explains residential property taxes using this formula:
Fair Market Value × 9.5% Assessment Rate × Applicable Mill Levy = Property Tax
The county's published example uses a 73.5 mill levy. At that levy, a $100,000 property would generate approximately $698 in annual property tax. Actual mill levies vary by taxing district, so investors should always retrieve the tax history and applicable levy for the specific parcel.
Using the county's example rate purely for illustration, a $350,000 property would generate roughly $2,444 per year in property taxes.
Lower carrying costs can improve both cash flow and long-term return.
Property taxes may also generally be deductible as a rental-property operating expense, subject to current tax law and the investor's individual circumstances.
That is one of several reasons investors should evaluate real estate on an after-tax basis, not simply compare gross rent with the mortgage payment.
Investors should consult a qualified tax professional regarding their specific situation.
6. Do Not Underestimate Insurance
Insurance is becoming a larger part of real-estate underwriting nationwide.
Actual premiums depend on coverage amount, replacement cost, deductible, claims history, property age, construction type and many other factors.
More importantly, a homeowners policy is not necessarily appropriate for an investment property.
Investors should obtain an actual landlord-policy quote before closing rather than plugging a generic insurance number into a spreadsheet and assuming it will be accurate.
Insurance is a real expense, but premiums paid for a rental property may generally be treated as a business expense for tax purposes.
Again, a deductible expense does not become free. A $2,000 insurance premium still costs $2,000.
The deduction simply reduces the property's taxable income subject to applicable tax rules.
That distinction is important when investors discuss the "tax advantages" of rental property.
7. Vacancy Still Matters
Even markets with strong rental demand have vacancy.
For preliminary underwriting, I generally want an investor to include a vacancy allowance rather than assume 12 months of perfect rent collection every year.
In my experience, a 5% vacancy allowance is a reasonable starting assumption for many stabilized long-term rentals. An unusual property, luxury home, seasonal property, rural property or property with limited tenant demand may deserve a higher assumption.
Vacancy also includes more than an empty house.
Turnover expenses, advertising time, cleaning, repairs and the period between residents can all reduce the property's effective income.
An investor planning to hold a property for 10 or 20 years should expect some periods to be better than others.
The objective is not to find a property that will never have a vacancy.
It is to own a property whose long-term income, equity growth and appreciation are sufficient to absorb normal operating fluctuations.
8. Maintenance and Capital Expenses
A common mistake is treating mortgage principal, interest, taxes and insurance as the property's only expenses.
Rental houses wear out over time.
Water heaters fail. Furnaces need repair. Appliances quit. Sewer lines develop problems. Roofs eventually need replacement. Flooring, paint and blinds wear out between residents.
For a preliminary analysis, I advise investors to estimate 10% of gross income for routine maintenance, depending on the age and condition of the property.
I also prefer to include a separate capital-expense reserve for large items.
A property that appears to cash-flow $300 per month but requires a $14,000 roof every 15 years is not really producing $300 per month unless some of that money is being reserved for future expenses.
At the same time, improvements can sometimes create wealth rather than simply consume it.
For example, an investor may purchase a dated property, improve kitchens, flooring, paint, landscaping or unit configuration, and create a property that supports higher rents and a higher resale value.
That is the difference between maintenance and value-add investing.
Maintenance preserves an asset.
Strategic improvements can increase its income or value.
9. Cody Has Seasonal Considerations
Cody is not purely a seasonal community, but tourism has a significant influence on the local economy.
Yellowstone National Park recorded more than 3.49 million recreational visits through August 2026, including approximately 856,000 visits during August alone.
That seasonal economy affects employment, housing demand and leasing patterns.
Long-term rentals generally have much less seasonal income volatility than vacation rentals, but timing can still matter. A property becoming vacant heading into winter may behave differently than the same property marketed during the spring or early summer.
Investors should therefore consider when a lease expires in addition to how much rent it produces.
Long-term investors also need to separate temporary market conditions from the long-term investment thesis.
One weak leasing season does not necessarily make a 15-year investment unsuccessful.
Likewise, one unusually strong year should not be projected indefinitely.
10. Single-Family Homes
Single-family houses are often the easiest investment property to understand—and currently one of the hardest Cody property types to make cash-flow at full retail pricing, but they still have significant advantages.
They generally have a broad resale market, attract longer-term residents, may experience lower turnover, and can benefit from long-term appreciation.
They can also create wealth through mortgage amortization.
If a resident's rent helps cover the mortgage each month, part of that mortgage payment may reduce the investor's loan balance.
Even if an investor receives little spendable cash each month, the resident may effectively be helping the investor acquire more equity in the property.
For example, if an investor's loan balance declines by $5,000 during a year, that $5,000 is economically different from $5,000 spent on insurance or repairs. It has increased the investor's ownership in the property.
Single-family houses may also benefit from appreciation because they compete with both investors and owner-occupants when eventually sold.
The problem remains acquisition cost.
A $400,000 or $500,000 house renting for $1,800 to $2,200 per month can be an attractive long-term asset while still being a weak immediate cash-flow investment.
An investor needs to decide whether the expected equity growth and appreciation justify tying up the capital.
11. Duplexes
Duplexes can make considerably more sense.
Instead of buying one rental-income stream along with the land, roof and infrastructure, the investor receives two streams of rent.
The economics become even better when some expenses are separately metered or paid directly by each resident.
Duplexes also give investors some protection from total vacancy. If one unit becomes vacant, the second unit can continue producing income.
For investors seeking stronger cash flow in Cody, I would generally want to analyze duplexes before similarly priced single-family homes.
Duplexes can also offer another wealth-building strategy: owner occupancy.
In some situations, an investor can live in one unit and rent the other, potentially gaining access to financing options that would not be available on a purely non-owner-occupied investment.
That can reduce the amount of cash required to control the asset and allow the resident in the second unit to offset part of the owner's housing expense.
Financing requirements vary, so buyers should confirm eligibility with their lender.
12. Apartments
Small apartment buildings can provide better economies of scale.
One roof, one parcel and one acquisition may generate income from four, eight, twelve or more units.
That can substantially improve the relationship between acquisition price and gross rental income.
Apartments also offer another important wealth-building opportunity.
Unlike most single-family homes, which are often valued largely through comparable sales, multifamily properties can be strongly influenced by their net operating income.
Increasing rents, reducing unnecessary expenses, billing utilities appropriately, improving occupancy or adding legitimate income streams may increase the property's value.
For example, if an investor can increase annual NOI by $10,000, the property's value may increase by substantially more than $10,000 depending on the capitalization rate buyers are willing to accept.
That creates the possibility of forced appreciation—creating additional value through better operations rather than simply waiting for the overall market to rise.
However, apartments come with additional management, maintenance and capital requirements.
The condition of the roof, plumbing, electrical systems, parking areas, common areas and utility configuration can dramatically affect the economics.
With apartments, investors should focus heavily on net operating income, not simply the advertised gross rents.
NOTE: properties with 1-4 units qualify for traditional mortgages. You will need a commercial loan for five or more units, which typically requires a much larger downpayment, variable rate interest, and other considerations.
13. Mobile and Manufactured Homes
Manufactured housing can sometimes produce some of the strongest rent-to-purchase-price ratios in the Big Horn Basin.
But there is a major distinction between a manufactured home with land and a manufactured home sitting on a rented lot.
Lot rent can consume a substantial part of the property's income. I once bought a small mobile home in Juby's for $3,000 and rented it for $800 a month. That's high cash flow, but remember that $425 of the rent was eaten up by lot rent, then I had higher maintenance costs because it was an old trailer.
Investors should also verify title, age, financing eligibility, park rules, utility responsibility, insurance availability and the physical condition of older homes.
The lower purchase price can create attractive opportunities.
Manufactured housing can sometimes produce stronger current cash flow than higher-priced conventional housing, although appreciation, financing and resale characteristics may differ considerably.
An investor who prioritizes cash flow may therefore reach a completely different conclusion than an investor who prioritizes long-term appreciation.
Neither strategy is inherently right or wrong.
They simply produce wealth differently.
14. Commercial Investment Opportunities
Commercial property operates differently from residential investment property.
A good commercial tenant may sign a longer lease and pay some or all operating expenses under a modified-gross or triple-net structure.
That can create attractive income.
Commercial real estate also offers significant value-add possibilities.
An investor may buy a vacant or under-rented property, renovate it, secure stronger tenants, negotiate longer leases or restructure operating expenses.
If those actions substantially increase net operating income, they may also substantially increase the value of the building.
The risk is that commercial vacancies can last much longer.
Investors should analyze the building's suitability for other businesses, parking, signage, zoning, tenant-improvement costs and the depth of the local tenant market.
A property occupied by a successful tenant at an attractive cap rate can be a very different investment from a vacant specialized building that needs six months of improvements before another tenant can use it.
15. Short-Term Rental vs. Long-Term Rental
Cody's tourism industry makes vacation rentals appealing, but investors should not buy a property assuming it can automatically become an Airbnb or VRBO.
The City of Cody requires short-term rentals to be registered, inspected for fire and life safety, and renewed annually. Short-term rentals are allowed only in specified zoning districts, with additional owner-occupancy restrictions in some residential zones. Even if zoning allows short-term, an HOA may restrict them. Do your research!
Long-term rentals generally provide more predictable income and lower operating involvement.
Short-term rentals can sometimes generate substantially more gross revenue during peak season, but they also bring higher furnishing, cleaning, utilities, management, insurance and vacancy costs.
They should be analyzed as an entirely different business model.
Tax treatment may also differ depending on property use, services provided, personal use and other factors.
Anyone purchasing primarily for tax advantages should speak with a tax professional before relying on those assumptions.
16. Cody vs. Powell for Investors
Powell deserves serious consideration.
Redfin's three-month median sale price through October 2026 was approximately $364,746 in Powell, compared with $462,129 in Cody.
In other words, the typical Powell sale price was roughly 21% lower than Cody's.
Our marketed-rental sample showed Cody rents averaging approximately 12% more than Powell.
That mismatch is important.
If purchase prices are 20% lower but achievable rents are only 10% to 15% lower, Powell may produce a better rent-to-purchase-price ratio on comparable properties.
That can improve immediate cash flow and reduce the amount of capital required.
Cody, however, may offer different appreciation, resale and demand characteristics.
That creates a useful distinction:
Powell may sometimes offer better income economics, while Cody may offer different long-term growth characteristics.
That is not a universal rule. It is something investors should analyze property by property.
A good investment decision considers both the income the property produces today and the wealth it may create over the full holding period.
17. Example Cody Investment Analysis
Consider a hypothetical Cody three-bedroom rental purchased for $350,000.
Assume:
Purchase price: $350,000
Down payment: 25%
Loan: $262,500
Interest rate: 7.50%
Loan term: 30 years
Monthly rent: $1,900
| Item | Annual Amount |
|---|---|
| Gross rent | $22,800 |
| 5% vacancy allowance | -$1,140 |
| 8% maintenance allowance | -$1,824 |
| 5% capital reserve | -$1,140 |
| 8% management allowance | -$1,824 |
| Estimated property taxes | -$2,444 |
| Insurance assumption | -$1,800 |
| Estimated NOI | $12,628 |
| Estimated annual principal & interest | -$22,025 |
| Estimated cash flow | -$9,397/year |
| Estimated monthly cash flow | -$783/month |
At first glance, that looks like a poor investment.
And for an investor whose primary objective is immediate income, it probably is.
But the analysis should not stop there.
Part of the mortgage payment reduces principal.
The property may appreciate over time.
Rents may increase.
Certain operating expenses, mortgage interest and depreciation may affect the investor's taxable income.
And an investor may be able to improve the property or refinance later if financing conditions become more favorable.
Consider a simplified long-term illustration.
If a $350,000 property appreciated an average of 3% annually, it would theoretically be worth approximately $470,000 after 10 years.
That would represent roughly $120,000 in market appreciation.
Meanwhile, a 30-year amortizing loan would also have a lower balance after 10 years, creating additional equity through principal reduction.
Those two sources of wealth could potentially outweigh weak monthly cash flow.
But there are two major cautions.
First, appreciation is not guaranteed. Property values can stagnate or decline.
Second, an investor must have sufficient cash reserves and income to comfortably support any planned negative cash flow.
Buying a property that costs $800 every month with the hope that appreciation eventually rescues the investment is very different from intentionally accepting modest cash flow as one component of a well-capitalized long-term strategy.
That is why we should evaluate at least four separate numbers:
1. Cash flow – What goes into or comes out of your pocket each month?
2. Principal reduction – How much of the debt is being paid down?
3. Appreciation or value creation – How much might the property value increase naturally or through improvements?
4. Tax impact – How does ownership affect your taxable income based on your individual situation?
Together, those provide a much more complete picture of the property's potential total return.
18. The Tax Component of Rental Real Estate
Rental property can offer tax benefits that other investments may not provide in the same way.
Depending on the investor's circumstances and current tax law, deductible expenses may include items such as:
Mortgage interest
Property taxes
Insurance
Property-management fees
Repairs and maintenance
Professional services
Certain travel and business expenses
Depreciation of qualifying property
Depreciation is particularly important because it may allow an investor to deduct a portion of the building's cost over time even though the property may actually be increasing in market value.
However, tax treatment is complicated.
Deductibility can depend on whether an investor is considered active or passive, income level, personal use, ownership structure, basis, improvements, depreciation recapture and many other factors.
The right way to look at taxes is:
Tax benefits can improve a good investment. They should not be used to justify a bad one.
Investors should have a qualified CPA or tax adviser evaluate their individual circumstances.
19. The Biggest Mistakes Cody Investors Make
One of the biggest mistakes is judging a property only by monthly cash flow.
Another is doing exactly the opposite—ignoring poor operating results because someone says, "Real estate always appreciates."
Both approaches are incomplete.
The biggest mistakes I see include:
Buying based on gross rent instead of net income
Assuming appreciation will rescue a bad deal
Looking only at year-one cash flow and ignoring long-term equity growth
Underestimating maintenance and capital expenditures
Failing to verify actual taxes and insurance
Assuming an advertised rent is achievable
Buying a short-term rental without verifying regulations
Ignoring deferred maintenance
Underestimating vacancy and turnover
Overestimating tax benefits
Failing to distinguish deductible expenses from actual cash savings
Ignoring financing structure
Falling in love with the property before completing the investment analysis
The best investment property is not necessarily the nicest house.
And it is not necessarily the property with the highest monthly cash flow.
It is the property where the purchase price, financing, realistic rent, operating expenses, equity growth, risk and long-term objectives work together.
20. Before You Buy, Understand How the Property Will Build Wealth
Cody and the Big Horn Basin can still offer good real-estate investment opportunities.
But the easy deals are harder to find.
At today's prices and interest rates, investors need to be more selective, more realistic about rent and more careful about operating expenses.
Strong immediate cash flow may be difficult to achieve on many Cody properties.
That does not mean real-estate investing no longer works.
A property can potentially build wealth through several channels at the same time:
Cash flow + principal paydown + appreciation + tax benefits + rent growth + value creation.
Different properties will rely on those components in different proportions.
A manufactured home might produce strong cash flow but limited appreciation.
A Cody single-family home might produce little cash but stronger long-term equity potential.
A duplex may provide a balance of both.
A small apartment building may allow an investor to create additional value by increasing net operating income.
There is no single metric that identifies the best investment.
The objective is to understand your goals and exactly how you expect it to make money.
That is where working with someone who understands both the sales side and the property-management side of an investment can make a substantial difference.
American West Realty & Management can help analyze a property before you buy it, including realistic long-term rent, expected operating costs, property-management considerations, financing assumptions and the different ways the property may contribute to your long-term investment goals.
Considering an investment property in Cody, Powell or elsewhere in Park County? Contact American West Realty & Management for an investment-property analysis and property-management consultation before you make the offer.
Related resources: Should You Rent or Sell Your Home in Cody, Wyoming
Market data and assumptions in this article are current through November 2026 unless otherwise indicated. Investment returns, appreciation and future rents cannot be guaranteed. Tax examples are general information only and should not be considered tax advice. Market averages should not be used as a substitute for a property-specific rental analysis, insurance quote, financing quote, tax review or investment analysis.